Bank Alfalah Limited (PSX: BAFL) published its results for the three and nine months to 30 September 2026 on 22 October 2026. Figures below are for the bank on its own (unconsolidated). Per-share figures reflect the share split earlier this year, which halved the face value to Rs 5 and doubled the number of shares to 3.15 billion.
The headline: a profit after tax of Rs 9.29 bn, or Rs 2.95 a share, for July to September, up 50.7% from Rs 6.16 bn (Rs 1.96) a year earlier. For the nine months, profit rose 42.8% to Rs 30.6 bn (Rs 9.71 a share against Rs 6.80). The board declared an interim cash dividend of Rs 1.50 a share (30%), taking the nine-month total to Rs 4.50 against Rs 3.75 a year earlier (adjusted for the split).
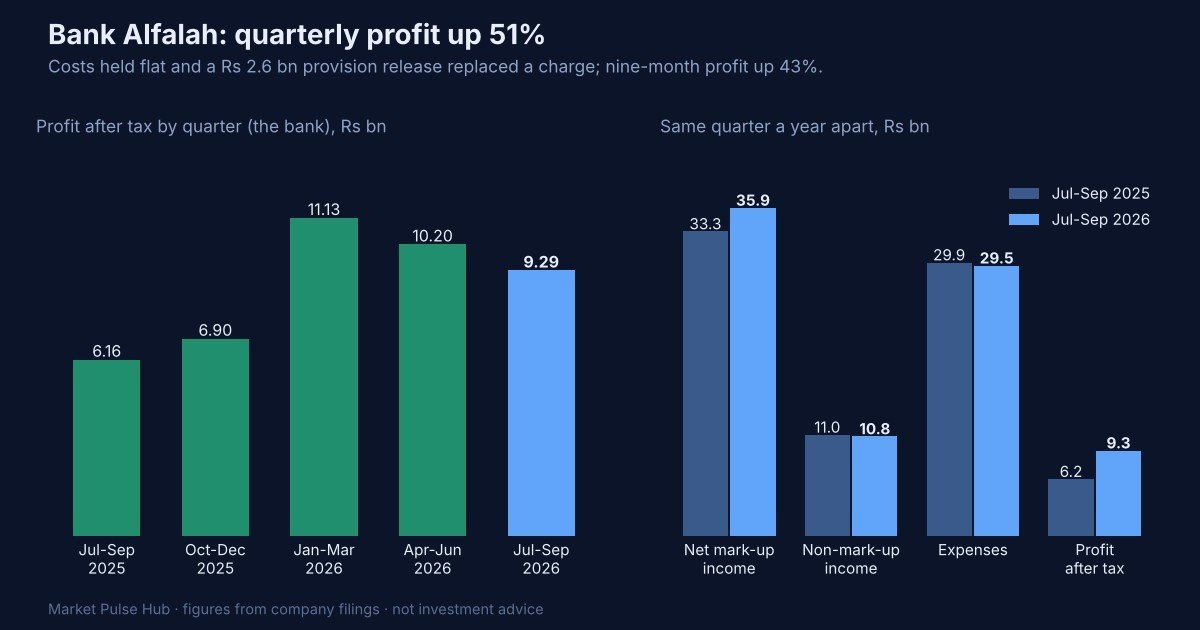
The quarter in numbers
| Rs M | Jul to Sep 2026 | Jul to Sep 2025 | Change |
|---|---|---|---|
| Mark-up / interest earned | 87,910 | 81,664 | +7.6% |
| Mark-up / interest expensed | (52,055) | (48,385) | +7.6% |
| Net interest income | 35,854 | 33,279 | +7.7% |
| Fee and commission income | 5,159 | 4,150 | +24.3% |
| Foreign exchange income | 4,511 | 3,573 | +26.3% |
| Income from derivatives | 938 | 545 | +72.0% |
| Gain / (loss) on securities | (355) | 2,063 | loss |
| Dividend and other income | 586 | 680 | −13.8% |
| Total non-interest income | 10,838 | 11,011 | −1.6% |
| Operating expenses and other charges | (29,527) | (29,875) | −1.2% |
| Profit before credit loss allowance | 17,166 | 14,415 | +19.1% |
| Credit loss allowance | 2,567 reversal | (1,051) charge | |
| Profit before tax | 19,732 | 13,364 | +47.7% |
| Tax (effective rate 52.9% against 53.9%) | (10,445) | (7,200) | +45.1% |
| Profit after tax | 9,287 | 6,165 | +50.7% |
| Earnings per share, Rs | 2.95 | 1.96 | +50.5% |
What drove the result
Steady interest income. Net interest income rose 7.7% in the quarter to Rs 35.9 bn, and 5.5% over nine months to Rs 104.8 bn. The bank credits higher average current account balances and better margins on its loans.
Fees and foreign exchange up, trading down. Fees rose 24% and foreign exchange income 26% in the quarter. Securities, which produced a Rs 2.1 bn gain a year earlier, showed a Rs 0.4 bn loss, so total non-interest income was slightly lower. Over nine months, though, non-interest income rose 31% to Rs 46.2 bn, helped by Rs 17.5 bn of capital gains booked mainly in the first half.
Costs held flat. Expenses fell 1% in the quarter and rose only 4.1% over nine months. The bank’s cost-to-income ratio improved to 58.1% for nine months from 62.6%; for the quarter alone it was about 63% against 67%.
Provisions turned into a release. The bank released Rs 2.6 bn of credit loss allowances in the quarter, against a Rs 1.1 bn charge a year earlier. That swing of about Rs 3.6 bn explains more than half of the rise in pre-tax profit.
The balance sheet
- Deposits growing. Deposits were Rs 2.62 trillion, up 20.8% from a year earlier and 4.8% since December. Current accounts, which pay no interest, were Rs 1.10 trillion, up 16.9% from a year earlier.
- Loans up, investments down. Gross loans rose 11.3% from a year earlier to Rs 1.20 trillion, from SME, agriculture and consumer lending. Investments fell to Rs 1.74 trillion from Rs 2.17 trillion in December, which is the main reason total assets shrank 12% to Rs 3.37 trillion.
- Asset quality and capital. The infection ratio was 3.5% with coverage of 106.9%. The capital adequacy ratio was 14.79%. Equity was Rs 194.8 bn, slightly lower than in December after dividends.
- Ratings. PACRA rates the bank AAA for the long term.
Valuation snapshot
At the 28 October close of Rs 57.88:
| Measure | Value |
|---|---|
| Earnings per share, last 12 months (October 2025 to September 2026) | about Rs 11.9 |
| Price to earnings | about 4.9 times |
| Book value per share | about Rs 61.8, so price to book of about 0.94 |
| Dividends in the last 12 months (Rs 1.50 final for 2025 plus three Rs 1.50 interims, split-adjusted) | Rs 6.00, a yield of about 10.4% |
| Market value (3.15 billion shares) | about Rs 183 bn |
| Share price, last 52 weeks, adjusted for the split | low about Rs 50.9, high about Rs 67.8 |
After the split the share trades just under its book value and at about 5 times earnings, with a dividend yield above 10%. It is close to the middle of its split-adjusted 52-week range.
What to watch next
- Provision releases. They lifted this quarter’s profit; a return to charges would cut into it.
- Trading income. Capital gains were large in the first half and turned into a small loss in the third quarter.
- Margins. With the policy rate at 11.5% after an increase in April, whether net interest income keeps growing.
- Costs. The bank expects to keep improving its cost-to-income ratio while still investing in technology.
- Dividends. Rs 1.50 a quarter so far this year; a final dividend would come with the annual results.
The bottom line
Bank Alfalah’s profit rose by half in the third quarter, driven by steady interest income, flat costs and a swing from provision charges to releases. Over nine months, profit is up 43% and the cost-to-income ratio has improved by more than four points. The share trades near book value with a yield above 10%.
You can follow BAFL’s price, Pulse Score, dividend history, results calendar and off-market trades in the Market Pulse Hub dashboard under PSX.
Bilal, Market Pulse Hub
Source: Bank Alfalah Limited, quarterly report for the nine months ended 30 September 2026 (directors’ review and unaudited unconsolidated condensed interim financial statements). October to December 2025 profit is derived from the 2025 annual result less the nine-month figure. Prices from the PSX data portal; prices before the April 2026 split are halved for comparison. Twelve-month, per-share and valuation figures are our calculations. This article is for education and information only and is not investment advice.