Fatima Fertilizer Company Limited (PSX: FATIMA), one of Pakistan’s main urea and nitrogen fertilizer producers, announced its results for the three months to 30 September 2026 after a board meeting on 28 October 2026. Its financial year runs to December, so this is the third quarter of 2026.
The headline: a group profit after tax of Rs 9.52 bn, or Rs 4.53 a share, down 20.5% from Rs 11.98 bn (Rs 5.70) a year earlier. The company’s own operations did better than that suggests: gross profit rose 24%. What fell away was other income. The board declared no dividend, bonus or right shares.
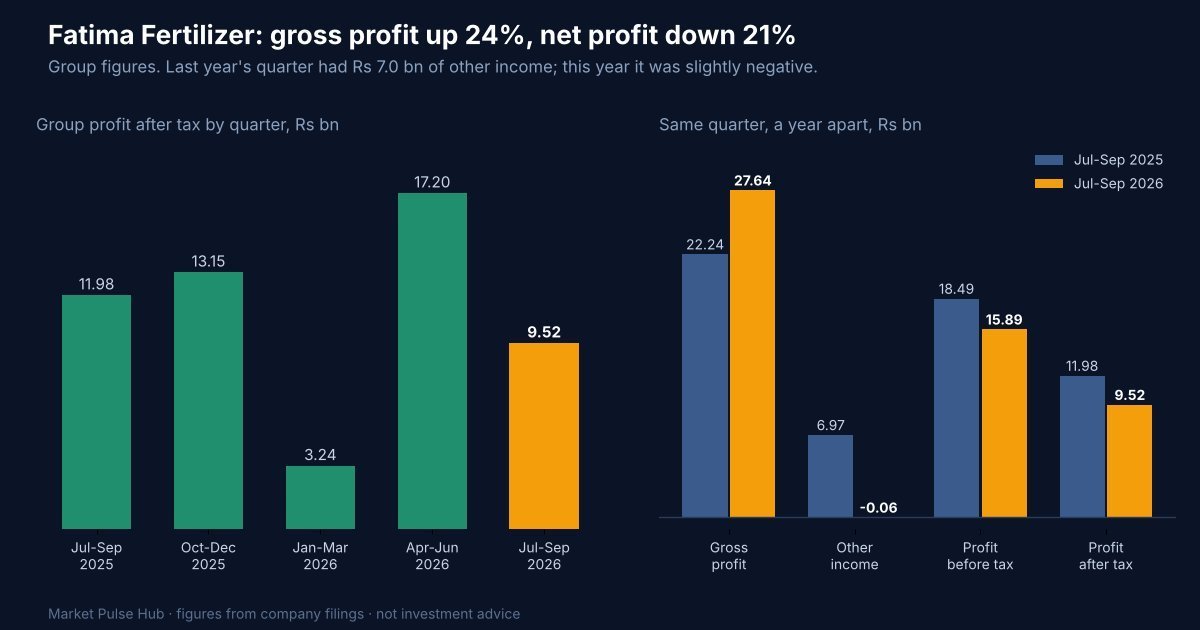
The quarter in numbers (group)
| Rs M | Jul to Sep 2026 | Jul to Sep 2025 | Change |
|---|---|---|---|
| Sales | 63,934 | 62,899 | +1.6% |
| Cost of sales | (36,297) | (40,660) | −10.7% |
| Gross profit | 27,637 | 22,239 | +24.3% |
| Gross margin | 43.2% | 35.4% | up 7.8 points |
| Distribution cost | (4,913) | (4,525) | +8.6% |
| Administrative expenses | (3,407) | (2,573) | +32.4% |
| Finance cost | (1,519) | (1,999) | −24.0% |
| Other operating expenses | (1,480) | (1,549) | −4.4% |
| Profit before other income and associates | 16,317 | 11,593 | +40.7% |
| Other income | (59) | 6,967 | gone |
| Share of loss from associates | (364) | (66) | larger loss |
| Profit before tax | 15,894 | 18,494 | −14.1% |
| Tax (effective rate 40.1% against 35.2%) | (6,375) | (6,518) | −2.2% |
| Profit after tax | 9,519 | 11,976 | −20.5% |
| Earnings per share, Rs | 4.53 | 5.70 | −20.5% |
What drove the result
The fertilizer business earned much more. Sales were almost unchanged at Rs 63.9 bn, but cost of sales fell 11%, lifting the gross margin from 35% to 43%. Gross profit rose by Rs 5.4 bn. After running costs, the profit the business made before other income and associates rose 41%, helped by a 24% fall in finance cost as the company repaid debt. The filing does not explain the lower cost of sales; cheaper gas or raw materials, or a better product mix, would all have this effect.
Other income disappeared. A year ago the group booked Rs 6.97 bn of other income in the quarter; this time it was a small negative, minus Rs 59 M. That single line explains more than the whole fall in profit. The filing does not break it down, but the balance sheet gives a clue: short-term investments, which typically earn interest, fell from Rs 90.0 bn in December to Rs 46.3 bn, much of the money going to repay loans and into long-term investments.
A higher tax rate. Tax took 40% of pre-tax profit against 35% a year earlier, so the fall in profit after tax (21%) was steeper than the fall before tax (14%).
Nine months still slightly ahead. For January to September, group sales rose 9% to Rs 194.5 bn, gross profit rose 22% to Rs 78.2 bn and profit after tax rose 3.6% to Rs 29.96 bn (Rs 14.27 a share against Rs 13.77), despite other income falling from Rs 12.7 bn to Rs 4.6 bn.
The company on its own
The parent company’s standalone accounts look weaker. Its profit for the quarter was Rs 7.11 bn (Rs 3.38 a share) against Rs 9.54 bn (Rs 4.54), down 25%, and for nine months Rs 20.33 bn (Rs 9.68) against Rs 26.79 bn (Rs 12.76), down 24%. The standalone figures for last year have been restated, and the filing pages do not say why, so they are not directly comparable with figures published a year ago. Standalone other income fell from Rs 7.14 bn to Rs 1.48 bn in the quarter.
The balance sheet and cash
- Much less long-term debt. The group repaid Rs 37.0 bn of long-term loans in nine months. Long-term finance, including the current portion, fell from about Rs 40.5 bn in December to about Rs 9.1 bn. Short-term borrowing rose to Rs 41.9 bn from Rs 32.4 bn.
- Investments moved from short to long term. Short-term investments fell from Rs 90.0 bn to Rs 46.3 bn, while long-term investments rose from Rs 10.7 bn to Rs 36.6 bn; the cash flow shows Rs 24.4 bn spent on long-term investments. The filing pages do not name them.
- More stock, fewer receivables. Stock in trade rose from Rs 64.2 bn to Rs 89.0 bn, while trade debts fell from Rs 32.3 bn to Rs 10.7 bn.
- Strong cash from operations. Cash generated from operations was Rs 64.7 bn in nine months against Rs 40.3 bn, though Rs 32.9 bn went in tax. Capital spending rose to Rs 15.6 bn from Rs 5.4 bn.
- Equity rose to Rs 194.6 bn, about Rs 92.65 a share.
The dividend
No dividend was declared with these results. A year ago the company paid an interim dividend of Rs 3.50 a share with its half-year results; this year there has been none so far, and the only payout in 2026 has been the Rs 2.50 final dividend for 2025. With money going into debt repayment, long-term investments and higher capital spending, the company appears to be keeping cash. Shareholders will look to the full-year results, due early next year, for the next payout.
Valuation snapshot
At the 28 October close of Rs 135.18, up 2.4% on the day of the result:
| Measure | Value |
|---|---|
| Group earnings per share, last 12 months (October 2025 to September 2026) | about Rs 20.5 |
| Price to earnings | about 6.6 times |
| Price to book | about 1.5 times |
| Dividends declared, last 12 months | Rs 2.50 a share, a yield of about 1.8% |
| Market value (2.1 billion shares) | about Rs 284 bn |
| Share price, last 52 weeks | low Rs 120.00, high Rs 192.80 |
The stock is about 30% below its 52-week high. On earnings it is not expensive, but with no interim dividend this year the yield is low for a fertilizer company, which is a big part of why investors usually own the sector.
What to watch next
- Gross margin. The rise to 43% is the strongest part of this result. Whether it holds depends on gas prices and supply, and on urea prices.
- Other income. Whether it recovers as investments mature or stays low now that short-term investments have been halved.
- The long-term investments. What the Rs 24.4 bn went into, and whether the growing share of losses from associates is a one-off.
- The dividend. Whether the full-year results bring a larger payout to make up for the missing interim.
The bottom line
Fatima’s fertilizer operations had a strong quarter: a much better margin, 41% more profit from the business itself and lower interest costs after a large debt repayment. But last year’s quarter was flattered by Rs 7 bn of other income, and with that gone, along with a higher tax rate and no dividend, the headline profit fell 21%. Over nine months the group is still slightly ahead of last year.
You can follow FATIMA’s price, Pulse Score, dividend history, results calendar and off-market trades in the Market Pulse Hub dashboard under PSX.
Bilal, Market Pulse Hub
Source: Fatima Fertilizer Company Limited, unaudited condensed interim consolidated and standalone financial statements for the nine months ended 30 September 2026, filed with the Pakistan Stock Exchange on 28 October 2026. Earlier quarters from company filings. Prices from the PSX data portal. Per-share, twelve-month and valuation figures are our calculations. This article is for education and information only and is not investment advice.