Fauji Fertilizer Company Limited (PSX: FFC), Pakistan’s largest urea producer, announced its results for the nine months to 30 September 2026 on 28 October. The July to September quarter was the strongest of the past five: profit for FFC’s shareholders at group level rose 16% to Rs 28.4 bn, or Rs 19.72 a share. The board also declared an interim cash dividend of Rs 18.50 a share, on top of Rs 23.00 already paid this year.
FFC reports on a calendar year, so this filing covers the first nine months of 2026 and the third quarter. Below we look at both, using the company’s unaudited statements. “Group” (consolidated) figures include FFC’s subsidiaries and its share of associated companies; “standalone” figures cover FFC’s own fertilizer business.
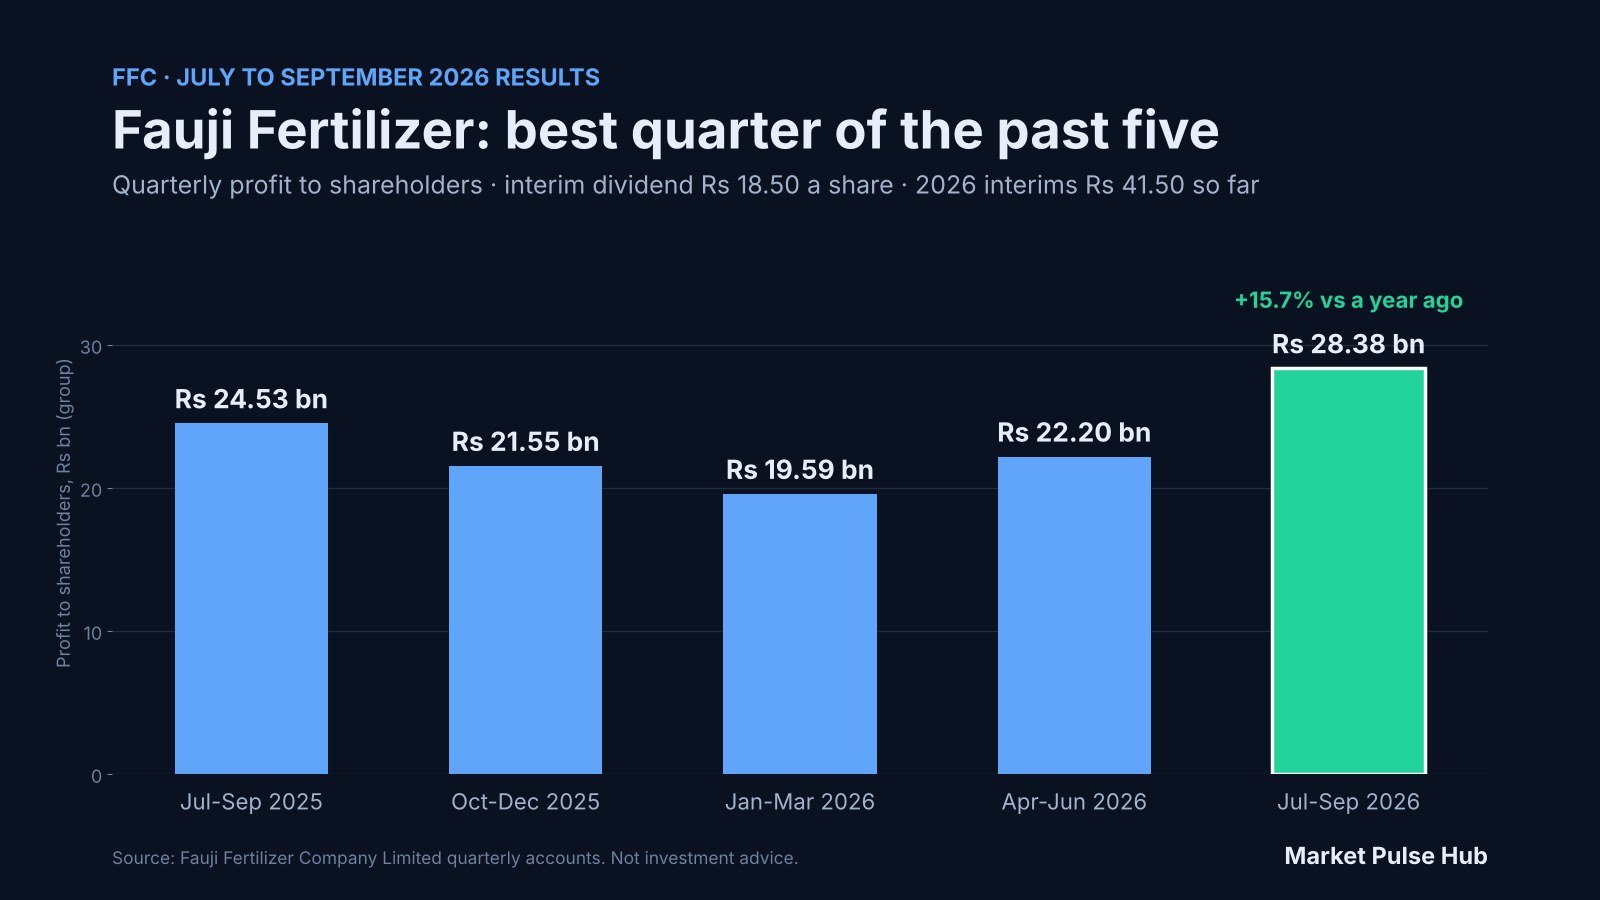
The results at a glance
| Group (consolidated), Rs bn | Jul to Sep 2026 | Jul to Sep 2025 | Change | 9 months 2026 | 9 months 2025 | Change |
|---|---|---|---|---|---|---|
| Net turnover | 143.11 | 140.20 | +2% | 373.24 | 322.50 | +16% |
| Gross profit | 49.04 | 45.65 | +7% | 124.64 | 108.45 | +15% |
| Share of profit of associates and joint venture | 6.72 | 4.19 | +60% | 17.88 | 17.41 | +3% |
| Profit before tax | 42.77 | 39.06 | +9% | 108.62 | 98.83 | +10% |
| Profit to FFC shareholders | 28.38 | 24.53 | +16% | 70.18 | 61.62 | +14% |
| Earnings per share (Rs) | 19.72 | 17.24 | +14% | 48.77 | 43.30 | +13% |
The fertilizer business: margins did the work this quarter
| Standalone, Rs bn | Jul to Sep 2026 | Jul to Sep 2025 | Change | 9 months 2026 | 9 months 2025 | Change |
|---|---|---|---|---|---|---|
| Net turnover | 127.69 | 127.25 | flat | 327.30 | 282.70 | +16% |
| Gross profit | 42.94 | 39.22 | +9% | 106.65 | 92.83 | +15% |
| Gross margin | 33.6% | 30.8% | 32.6% | 32.8% | ||
| Distribution cost | 10.23 | 8.60 | +19% | 27.95 | 23.42 | +19% |
| Finance cost | 3.00 | 1.56 | +93% | 7.29 | 4.96 | +47% |
| Other income (mostly investment income) | 9.27 | 6.27 | +48% | 37.51 | 34.43 | +9% |
| Profit after tax | 22.32 | 19.18 | +16% | 64.16 | 57.64 | +11% |
| Earnings per share (Rs) | 15.51 | 13.48 | +15% | 44.59 | 40.50 | +10% |
Over nine months, revenue grew 16%, which the company puts down mainly to higher urea sales volumes. In the third quarter alone revenue was flat, but gross margin widened from 30.8% to 33.6%, lifting gross profit by 9%. Higher investment income and other income (up 48% in the quarter) added the rest, more than covering a near doubling of finance costs after new borrowing.
The operating picture
| Thousand tonnes, nine months | 2026 | 2025 | Change |
|---|---|---|---|
| Pakistan urea market | 4,404 | 4,205 | +5% |
| FFC urea sales (offtake) | 2,160 | 1,955 | +10% |
| FFC share of the urea market | 49% | 46% | +2.5 points |
| Prilled urea production | 1,914 | about 1,876 | +2% |
| Granular urea production | 281 | about 331 | −15% (gas shortage) |
| Pakistan DAP market | 775 | about 799 | −3% |
| FFC DAP sales, including imports | 524 | about 540 | −3% |
FFC sold 10% more urea in a market that grew 5%, so it gained share and now supplies about half of Pakistan’s urea. The weak spots were gas: granular urea output fell 15% because of gas shortages, and DAP production at the Sona plant slipped to 586,000 tonnes from 622,000 because of raw material supply constraints and expensive phosphoric acid. The company also notes that geopolitical uncertainty keeps pushing up operating costs, which it is partly offsetting with cost controls.
Dividends: Rs 41.50 a share of interims so far in 2026
- New interim dividend: Rs 18.50 a share (185%).
- Already paid in 2026: interim dividends of Rs 8.50 and Rs 14.50, a total of Rs 23.00.
- Interims declared for 2026 so far: Rs 41.50 a share, about 7.7% of the 27 October share price of Rs 537.11.
- Record date: shareholders on the register on 8 November 2026. The share transfer books are closed from 9 to 11 November.
Cash flow and balance sheet: strong cash, but big new commitments
FFC’s own operating cash flow for the nine months was Rs 46.7 bn, against just Rs 2.9 bn a year earlier. A big reason is collections: money owed by customers fell from Rs 20.2 bn at the end of 2025 to under Rs 1 bn. At the same time stock in trade more than doubled, from Rs 38.2 bn to Rs 87.8 bn, which is worth watching as a sign of higher inventory or imported product on hand.
The cash went to several large uses:
- Rs 31.2 bn invested in PIA Equity Limited, FFC’s new stake in the national airline. Long-term investments rose from Rs 79.1 bn to Rs 110.4 bn as a result.
- Rs 28.2 bn of capital spending, more than double last year’s Rs 11.9 bn. Fixed assets grew from Rs 76.6 bn to Rs 99.6 bn.
- Rs 45.2 bn of dividends paid to shareholders.
To fund this, FFC drew Rs 30 bn of new long-term loans. Long-term borrowing including the current portion rose from Rs 61.3 bn to Rs 84.1 bn, which explains the higher finance cost. Even so, the company remains in a strong net cash position: short-term investments of Rs 170.7 bn and cash of Rs 5.3 bn comfortably exceed total borrowings of about Rs 102 bn. Dividends received from its group companies (Rs 23.7 bn over nine months) remain an important source of cash.
The share count also rose slightly, from 1,423 million to 1,439 million shares, after FFC issued shares as consideration for acquiring a further stake in FPCL, as shown in its statement of changes in equity. That is why earnings per share grew a little more slowly than profit.
Valuation snapshot
At the 27 October close of Rs 537.11:
| Measure | Value |
|---|---|
| Market value (1,439 million shares) | about Rs 773 bn |
| Group profit to shareholders, last four quarters | about Rs 91.7 bn, or about Rs 63.7 a share |
| Price to earnings, last four quarters | about 8.4 times |
| 2026 interim dividends declared so far | Rs 41.50 a share (about 7.7% of the price) |
| Share price, last 52 weeks | low Rs 471.40, high Rs 673.16 |
| Change over one year | about +12.5% |
What to watch next
- Gas supply. Shortages already cut granular urea output by 15%. Any further curtailment would hit volumes in the peak winter (rabi) season.
- The PIA investment. Rs 31 bn is a large commitment outside fertilizer. How the airline’s turnaround goes will matter for FFC’s returns and possibly for future dividends.
- Inventory. Stock in trade more than doubled to Rs 87.8 bn. It should come down as the rabi season sales arrive.
- Debt and finance costs. Borrowing is up Rs 23 bn this year. It is small against FFC’s investments, but finance costs have nearly doubled in the quarter.
- Fourth-quarter dividend. With profit up and strong cash, the final dividend for 2026 will show how much the PIA and capital spending commitments change the payout.
The bottom line
FFC delivered what investors expect from it: steady growth in urea volumes, its strongest quarterly profit of the past five quarters, and another generous dividend. The quarter’s margin improvement and market share gains are encouraging. The bigger change is on the balance sheet, where FFC is spending heavily on new projects and a large stake in PIA, and has started borrowing more to do it. The core fertilizer business looks healthy; the new investments are the part to follow over the coming quarters.
You can follow FFC’s price, Pulse Score, fair value estimate and any off-market block trades in the Market Pulse Hub dashboard under PSX.
Bilal, Market Pulse Hub
Source: Fauji Fertilizer Company Limited, unaudited financial statements for the nine months ended 30 September 2026, filed with the Pakistan Stock Exchange on 28 October 2026. Market share and per-share valuation figures are our calculations. Where the filing gives only a percentage change, last year’s tonnage is approximate. This article is for education and information only and is not investment advice.